6-Month T-Bill Rate: 4.47% at the Nov. 16 Auction
The 6-month T-bill sold at a 4.467% rate on Nov. 16, 2026 (CUSIP 912797XD4, matures May 20, 2027). $10,000 earns $217.89; a bank needs 4.83% APY to match.
6-month T-bill, Nov. 16 auction, CUSIP 912797XD4
Next auction: Monday, Nov. 23
- Investment rate
- 4.467%
- Up 0.174 from Nov. 9
- Discount rate
- 4.310%
- $97.821056 per $100
- $10,000 bill
- $9,782.11
- Pays $217.89 on May 20, 2027
- Bank APY to match
- 4.83%
- After 22% federal + 5% state tax
The 6-month Treasury bill sold at a 4.467% investment rate (4.310% discount rate) on Monday, Nov. 16, 2026. That is 0.174 points above the week before and the highest of the past year, above the Sept. 28 high of 4.441%, and about 0.6 points more than the same bill paid a year ago. Buy one now and you lock that rate until May 20, 2027.
We update this page after every 6-month auction from Treasury’s own results. Other terms: T-bill rates today (4 to 52 weeks), the 4-week T-bill rate, the 3-month T-bill rate and the 52-week T-bill rate.
Nov. 16 auction results
| 6-month (26-week) bill | |
|---|---|
| CUSIP | 912797XD4 |
| Auction date | Monday, Nov. 16, 2026 |
| High discount rate | 4.310% |
| Investment rate | 4.467% |
| Price per $100 | $97.821056 |
| Issue date | Thursday, Nov. 19, 2026 |
| Maturity date | Thursday, May 20, 2027 (182 days) |
| Offering size | $82 billion |
| Bid-to-cover ratio | 2.83 (normal for recent months) |
Compare the investment rate with a savings account’s or CD’s APY; the discount rate runs about 0.15 points lower on a 6-month bill. What each line means is in the glossary below.
The last 12 auctions
| Auction | Discount rate | Investment rate | Price per $100 | Bid-to-cover | Offered | CUSIP |
|---|---|---|---|---|---|---|
| Nov 16, 2026 | 4.310% | 4.467% | $97.821056 | 2.83 | $82B | 912797XD4 |
| Nov 9, 2026 | 4.145% | 4.293% | $97.904472 | 2.92 | $82B | 912797UX3 |
| Nov 2, 2026 | 4.150% | 4.298% | $97.901944 | 2.89 | $82B | 912797WX1 |
| Oct 26, 2026 | 4.210% | 4.361% | $97.871611 | 2.63 | $82B | 912797WW3 |
| Oct 19, 2026 | 4.220% | 4.372% | $97.866556 | 2.84 | $82B | 912797WV5 |
| Oct 13, 2026 | 4.200% | 4.351% | $97.876667 | 2.76 | $82B | 912797UE5 |
| Oct 5, 2026 | 4.165% | 4.314% | $97.894361 | 2.79 | $82B | 912797WU7 |
| Sep 28, 2026 | 4.285% | 4.441% | $97.833694 | 2.64 | $82B | 912797WM5 |
| Sep 21, 2026 | 4.155% | 4.303% | $97.899417 | 2.62 | $79B | 912797WL7 |
| Sep 14, 2026 | 4.060% | 4.203% | $97.947444 | 2.74 | $79B | 912797UD7 |
| Sep 8, 2026 | 3.890% | 4.023% | $98.033389 | 2.88 | $79B | 912797WK9 |
| Aug 31, 2026 | 3.885% | 4.018% | $98.035917 | 2.63 | $79B | 912797WD5 |
Holding a bill and want its details? Look it up in our T-bill CUSIP lookup, which lists every bill sold in the past year.
The past year
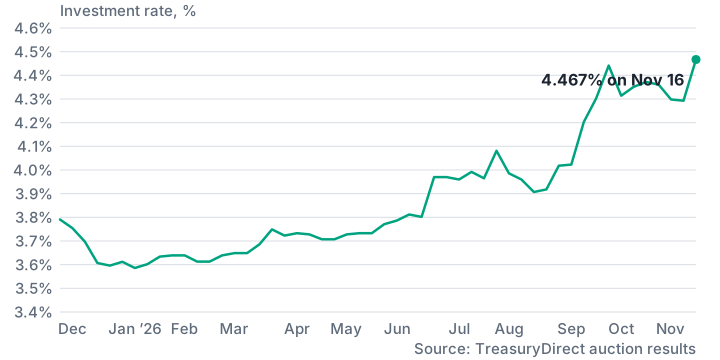
Nov. 17, 2025
3.833%
A year ago. The rate then drifted lower into the new year.
Jan. 5, 2026
3.586%
The low of the past twelve months. Through the spring it stayed between about 3.6% and 3.8%.
Late June 2026
About 3.8% → 3.97%
The first step up, in a single week. It stayed near 4% through August.
Sept. 8 to Sept. 28, 2026
4.02% → 4.441%
The second step: four higher auctions in a row. Over the same stretch the Fed raised its target range to 3.75%–4.00%, and the effective fed funds rate moved from 3.63% to 3.88% on Sept. 17.
Oct. 5 to Nov. 9, 2026
4.29% to 4.37%
Settled just below the September high, ending at 4.293% on Nov. 9, the lowest since Sept. 14.
Nov. 16, 2026
4.467%
Up 0.174 in one week, to the highest rate of the past year.
Why it moves more than a 4-week bill: the 4-week rate mostly reflects where the Fed’s rate is today, while the 6-month rate also prices in where investors think it will be over the next half-year. That is why the 6-month rate rose about 0.6 points over the year while the 4-week rate ended roughly where it started.
What $10,000 earns
T-bills sell at a discount and pay full face value at maturity; the difference is your interest. The Nov. 16 auction applied to $10,000 of face value:
| Amount | |
|---|---|
| You pay on Nov. 19, 2026 | $9,782.11 |
| You get back on May 20, 2027 | $10,000.00 |
| Interest over 182 days | $217.89 |
| After 22% federal tax | $169.96 |
| State and local tax | $0 (exempt) |
The same $9,782.11 in a savings account or CD for 182 days:
| Account and APY | Interest before tax | After 22% federal + 5% state tax |
|---|---|---|
| Savings, 0.38% (FDIC national average, Oct. 2026) | $18.52 | $13.52 |
| 6-month CD, 1.39% (FDIC national average, Oct. 2026) | $67.56 | $49.32 |
| Savings or CD at 4.00% | $193.19 | $141.03 |
| Savings or CD at 4.83% (break-even) | $232.82 | $169.96 |
So a bank account or CD needs about 4.83% APY to match this week’s bill with a 22% federal bracket and 5% state tax, or about 4.52% in a state with no income tax. Try your own brackets in the T-bill calculator.
A tax timing bonus. T-bill interest is taxed in the year the bill matures. A 6-month bill bought after early July matures the next year, so a bill bought this week puts its interest on your 2027 return. More in how T-bills are taxed.
6 months or a shorter bill?
| Bill | Latest investment rate | Compared with the 6-month bill |
|---|---|---|
| 13-week (3-month) | 4.257% (Nov. 16) | 0.21 points less |
| 26-week (6-month) | 4.467% (Nov. 16) | |
| 52-week (1-year) | 4.496% (Oct. 27) | 0.03 points more |
The real question is whether locking in for six months beats rolling two 3-month bills. If you bought a 13-week bill now, the one you buy when it matures in mid-February would need to pay about 4.63% to match the 6-month bill, about 0.37 points more than the 13-week rate today. So the 6-month bill wins unless short rates keep rising, and wins by more if they fall. If you would rather not pick one term, a 6-month T-bill ladder mixes them.
A year ago it was the other way round: in October 2025 the 13-week bill paid 3.818% and the 6-month only 3.760%, which usually means markets expect rates to fall. Today’s upward slope says they expect rates to hold or rise. See the full curve on the T-bill rates page.
| Option | What you earn | Rate locked? | Getting your money | State tax |
|---|---|---|---|---|
| 6-month T-bill | 4.467% investment rate (Nov. 16) | Yes, for 182 days | At maturity, or sell early through a broker | Exempt |
| 3-month T-bill | 4.257% investment rate (Nov. 16) | Yes, for 91 days | At maturity, or sell early | Exempt |
| 6-month CD | 1.39% APY national average; online banks pay far more (T-bills vs. CDs) | Yes, for 6 months | Early withdrawal penalty | Taxed |
| Savings account | 0.38% APY national average | No, the bank can change it any day | Any day | Taxed |
| Government money market fund | 7-day yield, usually close to short T-bill rates | No | Next business day | Partly exempt, depending on the fund’s holdings |
Averages are from the FDIC’s October 2026 table across all U.S. banks; the best online banks pay several times more, and money market funds post their own 7-day yields daily.
When the next auction is
Treasury auctions 6-month bills every week, on the same day as the 3-month bill:
| Step | Date | Detail |
|---|---|---|
| Announcement | Thursday, Nov. 19, 2026 (expected) | Offering size and CUSIP published |
| Auction | Monday, Nov. 23, 2026 (expected) | Non-competitive bids close 11:00 a.m. Eastern, competitive 11:30 a.m. |
| Issue | Friday, Nov. 27, 2026 (expected; Thanksgiving moves it from Thursday) | You pay; the bills mature on May 27, 2027 |
Holidays shift the schedule, so check TreasuryDirect’s upcoming auctions before you bid. We update this page once the results are out.
How to buy a 6-month T-bill
Either way you place a non-competitive bid: you accept the auction’s rate and are guaranteed the bills. The bills are the same; the accounts differ.
| TreasuryDirect | Brokerage account | |
|---|---|---|
| Minimum | $100, in $100 steps | Usually $1,000, in $1,000 steps |
| Selling before maturity | Hold 45 days, then transfer to a broker to sell | Sell any trading day, at that day’s price |
| Rolling into the next bill | Schedule reinvestment when you buy | Automatic rollover at some brokers, such as Fidelity and Schwab |
| Where the cash lands | Your linked bank account | Your brokerage cash balance |
If you might need the money before May, a brokerage is the easier place to hold it. Our guide to how to buy T-bills walks through each step.
Reading the auction numbers
- High discount rate 4.310%
- The rate the auction cleared at, as a markdown from face value on a 360-day year. Every winning bidder, including small non-competitive buyers, pays the same price.
- Investment rate 4.467%
- What you earn on the money you actually pay, on a 365-day year. About 0.15 points above the discount rate on a 6-month bill, because the discount is larger than on short bills.
- Price per $100 $97.821056
- What you pay for each $100 of face value.
- Bid-to-cover ratio 2.83
- Dollars bid for each dollar Treasury sold. 2.83 is down from 2.92 the week before and inside the 2.6 to 3.1 range of recent months, so demand is normal.
- CUSIP 912797XD4
- The nine-character ID of this specific bill, used by brokers and TreasuryDirect.
Our T-bill calculator converts any discount rate into an investment rate and dollar amounts.
How we got these numbers: auction results come from TreasuryDirect’s published results for each 26-week bill. We calculated the dollar examples from the official price per $100 and the savings examples with the same APY formula banks use. The chart is drawn from the last 52 auctions. Rates change every week; check the source before you act. See how we test and our disclaimer.
Questions people ask
What is the 6-month T-bill rate right now?
At the Nov. 16, 2026 auction the 26-week bill sold at a 4.310% high discount rate, which works out to a 4.467% investment rate. The investment rate is the one to compare with a savings account APY or a CD. The next auction is Nov. 23.
Is a 6-month T-bill the same as a 26-week T-bill?
Yes. Treasury names its bills in weeks, so the 6-month bill is officially the 26-week bill. It matures 182 days after it is issued.
How much does a $1,000 6-month T-bill cost?
At the Nov. 16, 2026 price of $97.821056 per $100, a $1,000 bill costs $978.21 and pays $1,000 at maturity on May 20, 2027, so you earn $21.79 over 182 days.
When do I pay tax on a 6-month T-bill?
The interest is taxed by the federal government in the year the bill matures, not the year you buy it. A bill bought in mid-November 2026 matures in May 2027, so the interest goes on your 2027 return. It is exempt from state and local income tax.
Is a 6-month T-bill better than a 6-month CD?
Usually, if you pay state income tax. The national average 6-month CD paid 1.39% APY in October 2026, according to the FDIC, and its interest is taxed by your state. Some online banks pay more than 4%, so compare the best CD you can get after tax with the bill's rate.
Sources
Update log
- Corrected the rate a second 3-month bill would need to match the 6-month bill: 4.63%, 0.37 points above the 13-week rate (we had 4.64% and 0.38).
- Updated with the Nov. 16, 2026 auction.
- Updated with the Nov. 9, 2026 auction.
- Updated with the Nov. 2, 2026 auction and reorganized the page so the rate, price and CUSIP come first.
- First published with the Oct. 26, 2026 auction.